The urgency is justified. AI has transformed digital infrastructure from an operational necessity into a strategic asset. Decisions once made by engineering teams are now discussed in boardrooms because they influence competitiveness, resilience, and long-term growth.
Yet I believe we are asking the wrong question. Much of the conversation still revolves around deployment speed, power availability and the technologies needed to support increasingly demanding AI workloads. Those are important discussions, but they focus on today’s challenges rather than tomorrow’s risks. The question that concerns me is not how quickly we can build, but whether what we build now will still be the right investment a decade from now.
The wrong investment question
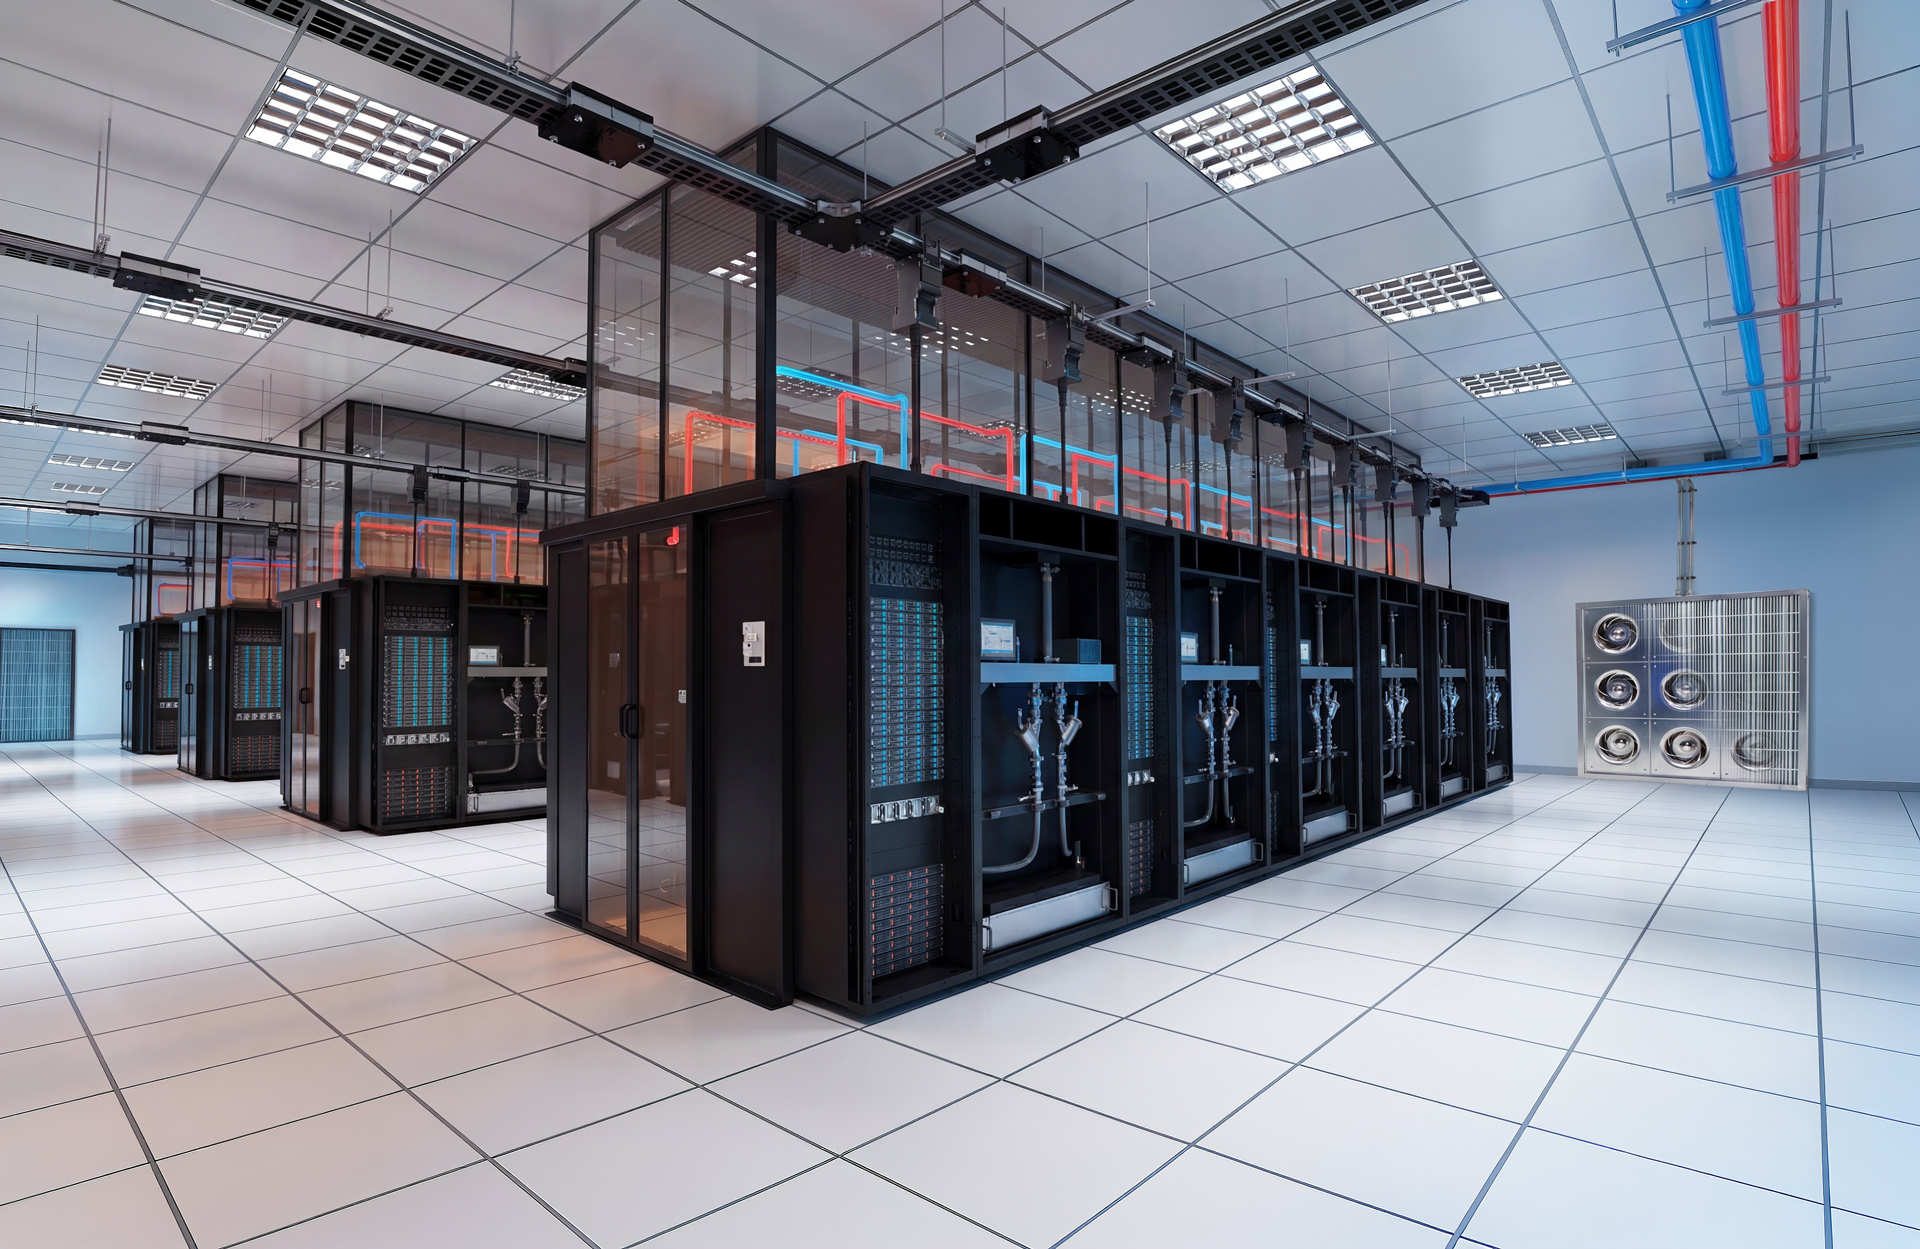
For decades, data center economics relied on a simple assumption: infrastructure would evolve far more slowly than the technology it supported. Electrical systems, cooling infrastructure, and power distribution were designed with lifecycles measured in decades, while investment decisions assumed those assets would retain their value throughout their depreciation period.
AI has fundamentally changed that equation. Technology is now evolving faster than the investment models designed to support it. Compute requirements continue to shift; power densities keep increasing and every new generation of accelerated computing challenges assumptions that seemed entirely reasonable only a short time ago. This is not a failure of engineering; it is the inevitable consequence of technology moving faster than the infrastructure built to support it.
When people talk about infrastructure risk, they usually mean outages, resilience, or operational reliability. They ask whether critical systems remain available, whether redundancy performs as intended and whether facilities can withstand failure. Those risks have always mattered.
But I believe the defining risk of the AI era is financial rather than technical. It is entirely possible to build a world-class facility that performs exactly as specified, meets every engineering requirement and delivers flawless operational performance, while simultaneously becoming a weaker investment than anyone anticipated when construction began. That possibility deserves far more attention than it receives.
The industry has become obsessed with deployment speed. Projects are celebrated for breaking ground early, reducing delivery schedules and bringing new capacity online ahead of competitors. But speed only creates value if you are deploying the right architecture. Building the wrong architecture faster simply accelerates commitment.
That is an uncomfortable thought because almost every commercial incentive favors speed over reflection. Investors want projects delivered quickly, customers need capacity as soon as possible and suppliers compete to shorten lead times. Few people are rewarded for asking whether today’s architecture will still be the right investment a decade from now.
Historically, flexibility has often been treated as an engineering preference. If budgets allowed, additional headroom could be designed into the infrastructure. Now flexibility is not an engineering luxury but a form of financial risk management.
The organizations that understand this are beginning to evaluate infrastructure differently. Instead of asking whether current design satisfies technical requirements, they ask whether today’s investment preserves tomorrow’s strategic options. Can electrical infrastructure evolve without wholesale replacement? Can cooling systems support technologies that have not yet entered commercial deployment?
Sure, these are engineering questions. But they are also investment questions. That distinction matters because the people making infrastructure decisions have changed. Twenty years ago, these discussions were largely led by engineering organizations. If a design met the technical requirements, the investment case was often straightforward.
As for now, technical performance is only one part of the conversation. CFOs want to understand lifetime capital exposure, sustainability leaders are looking at regulatory resilience, and boards are increasingly evaluating digital sovereignty alongside operational capability. Infrastructure decisions have become business decisions, which means engineering excellence alone is no longer enough.
Infrastructure has become a strategic business investment, yet we continue to evaluate it using assumptions inherited from a far more predictable technological era.
Perhaps that is understandable. Industries rarely recognize structural change while they are living through it. We naturally extend familiar planning models into unfamiliar environments because those models have served us well in the past. The difficulty is that AI is not changing only the technology, it’s changing the assumptions that sit underneath every infrastructure investment we make.
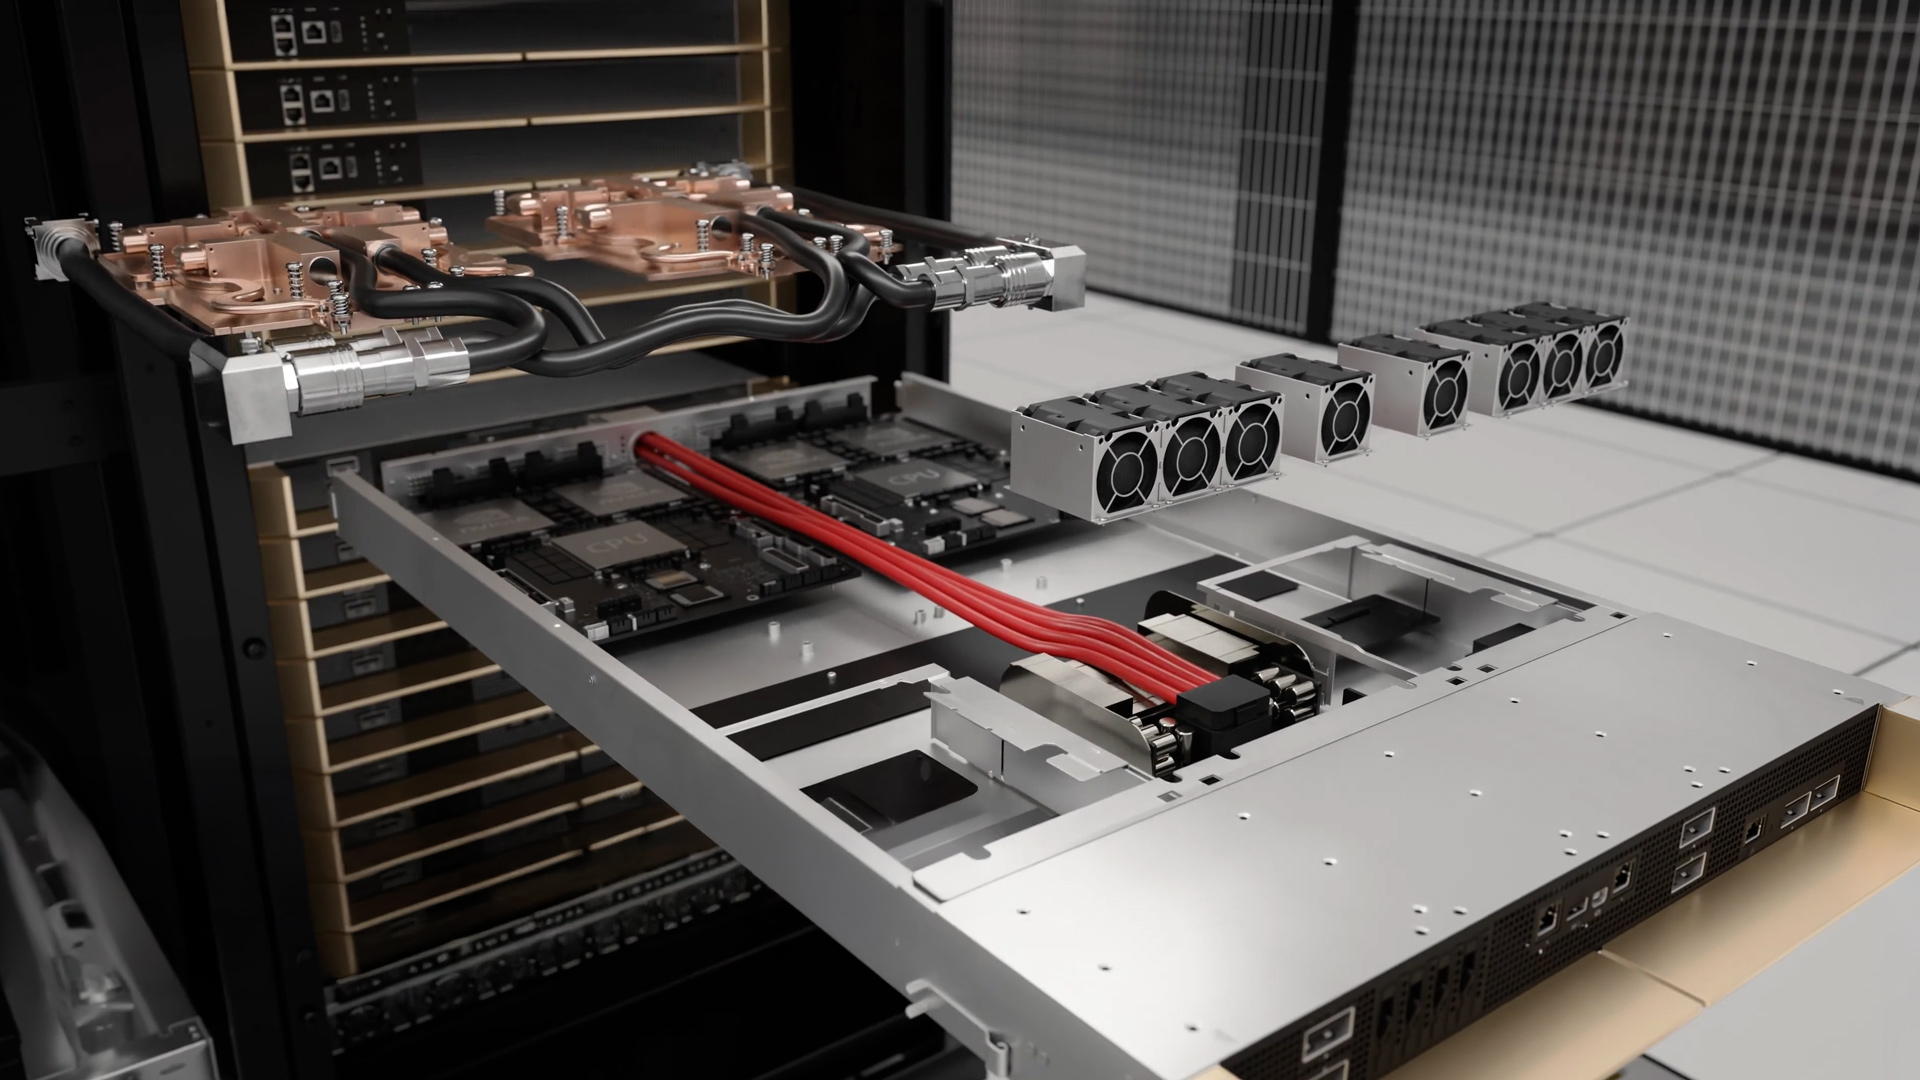
The problem isn’t lead time – It’s time itself.
Across Europe, organizations are trying to reconcile two timelines that were never designed to coexist.
On one side sits the business. AI strategies are measured in months, and competitive advantage is measured in quarters. Boards want to know when new capabilities will be available, customers expect rapid deployment and internal roadmaps assume computing capacity can expand almost as quickly as demand itself.
On the other side sits physical infrastructure. Substations cannot be accelerated by ambition. High-voltage equipment cannot be manufactured because a board has approved additional budget. Planning approvals, utility connections, transformers, and switchgear all move according to timelines measured in years rather than quarters. In many European markets, lead times for critical electrical infrastructure now extend well beyond eighteen months. The gap between those two timelines is becoming one of the defining challenges of the AI economy.
Yet even that is not what concerns me most. Long lead times are frustrating, but they are visible. They appear in project plans, procurement schedules, and board reports. Organizations can plan around them.
The real challenge is what happens while those projects are being delivered. Technology keeps moving. The assumptions made on day one does not remain frozen simply because construction has started. By the time a facility is commissioned, technology has often moved on. New GPU generations have emerged, power requirements have increased, cooling strategies have evolved and workloads have changed. A design that looked forward-looking when the investment was approved may already appear conservative by the time it enters operation. The infrastructure has not fallen behind; the pace of technological change has simply accelerated. And that fundamentally changes the investment equation.
After more than two decades working with critical infrastructure, I have learned that technology rarely creates the biggest surprises; our assumptions do.
One project, in particular, has stayed with me because it illustrates this better than any market forecast or analyst report. A financial services organization invested heavily in AI infrastructure. The engineering was sound, the design process was rigorous, and the business case had been carefully developed. By every conventional measure, it was exactly the kind of project our industry would describe as successful. Then the technology moved.
The GPU platform the organization ultimately needed demanded capabilities that had not been considered when the project was originally specified. Yet nothing had actually failed.
The infrastructure performed exactly as designed, and every engineering objective had been met. The infrastructure itself had not changed but the investment looked very different.
Suddenly, the organization faced decisions no leadership team wants to make after committing substantial capital. Should the project be retrofitted before completion, accepting additional cost and delay? Should performance ambitions be scaled back to match the existing infrastructure? Or should strategic AI programmes already promised to customers be postponed until the next investment cycle? None of those options represented success.
What stayed with me was not that the infrastructure had failed. It hadn’t. The assumptions behind the investment had.
We often talk about stranded assets when discussing the energy transition. Increasingly, I think we should also talk about stranded assumptions. Many of the facilities currently under construction will perform exactly as designed. They will achieve their availability targets. They will deliver excellent operational resilience and impressive efficiency.
The more important question is whether they will continue creating strategic value at the same pace that AI technology continues to evolve. Those are two very different measures of success.
For decades, our industry has been driven by optimisation: better efficiency, higher utilization, stronger performance, and lower cost per kilowatt. Those disciplines remain essential, but they are built on one assumption that the destination is relatively stable. AI has changed that.
When the destination itself keeps moving, adaptability becomes more valuable than optimisation. That is why I believe we spend too much time debating individual technologies and not enough time discussing capital exposure.
Liquid cooling, higher rack densities, and power quality all matter. But these are not the questions boards ask when approving investments measured in hundreds of millions of euros. They ask something much simpler.
Will this investment still create value a decade from now?
It is remarkable how rarely our industry answers that question directly.
Instead, we often present certainty where uncertainty would be more honest. We explain today’s specifications in great detail while quietly recognizing that nobody can predict the computing requirements of the next hardware generation with confidence.
Uncertainty is not the problem. Every major infrastructure investment involves uncertainty. The problem is behaving as though uncertainty disappears once a specification has been approved. If AI has taught us anything over the past few years, it is that technology is no longer waiting for investment cycles to catch up – it moves according to its own rhythm. Infrastructure has no choice but to adapt.
For many years, the relationship between customer and supplier has been largely transactional. Requirements are defined, solutions proposed, contracts signed and facilities delivered, with success measured against specifications agreed months or sometimes years earlier.
That model worked when technology evolved at roughly the same pace as the projects themselves. I am not convinced it works anymore.
Today, the most valuable partner is not necessarily the one offering the shortest delivery schedule or the lowest upfront cost. It is the one willing to challenge assumptions before they become expensive.
That sometimes means asking uncomfortable questions. Is current architecture flexible enough for technologies that do not yet exist? Are we optimizing today’s workload at the expense of tomorrows? Which assumptions are we treating as facts simply because they fit the current business case?
Those conversations are rarely easy. They may increase upfront investment, delay decisions, or even change the direction of a project. But they are far less expensive than discovering the real problem after the investment has already been made.
In my experience, trust has never been built by avoiding uncomfortable conversations. It is built by having them early enough that they still influence the outcome. That is one of the responsibilities our industry carries.
Technical expertise is no longer only about designing resilient electrical infrastructure or selecting the right cooling technology. It is also about translating engineering decisions into business consequences.
Too often, we assume good engineering automatically leads to good investment decisions. It does not. A technically excellent recommendation that cannot be explained in terms of business value is unlikely to influence a board’s decision. Equally, a financially attractive proposal that ignores long-term technical realities simply postpones risk instead of reducing it.
The real challenge is bringing those perspectives together. Infrastructure decisions are no longer owned by engineering alone. While technical teams remain focused on performance and resilience, financial leaders are increasingly evaluating the durability of the investment itself whether it will continue creating value throughout its intended lifetime, how exposed it is to additional capital requirements and how dependent it is on assumptions that may prove short-lived. Sustainability leaders are asking similar questions from a different perspective, examining whether today’s infrastructure can continue meeting tomorrow’s environmental and regulatory expectations. In reality, these are not separate conversations. They are different ways of assessing the same long-term investment.
That may be the biggest change our industry has experienced over the past decade. Data centers are no longer just technical infrastructure. They have become long-term strategic assets.
And strategic assets shouldn’t be judged solely by how efficiently they operate. They should also be judged by how well they retain their value tomorrow.
When I look ahead, I have little doubt about where technology is heading. AI models will continue demanding more power, higher densities, and increasingly sophisticated infrastructure, while new hardware platforms and cooling technologies will continue reshaping what “AI-ready” really means. That’s the easy prediction.
The more difficult question is how we will judge the investment decisions being made today. Every generation eventually discovers that it underestimated the future. We look back and wonder why demand was misread, why infrastructure became a constraint or why assets were optimised for assumptions that proved surprisingly short-lived.
I suspect our generation will have its own blind spot. Not because we underestimated AI, but because we underestimated how quickly it would challenge the assumptions behind the infrastructure built to support it. Many of the facilities commissioned this decade will still be operating well into the 2040s. They will remain reliable, continue supporting critical workloads and, from an engineering perspective, be considered highly successful. The more important question is whether they will still be delivering the strategic value their investors expected when construction began. Technical success and long-term investment success are not necessarily the same thing.
For years, our industry has asked whether infrastructure is ready for AI. Perhaps the more important question is whether our investment thinking is. The organisations that succeed over the next decade will not necessarily be those that build the largest AI infrastructure, but those that preserve optionality: recognising flexibility not simply as an engineering feature, but as a strategic capability. In an environment where technology refuses to stand still, the greatest competitive advantage is not certainty – it’s adaptability.